
ABN AMRO • From a monthly snapshot to daily risk management
A monthly snapshot can be highly accurate. But when reality changes every day, it remains just that: a snapshot. This is particularly relevant in asset-based lending, where the value and composition of assets can change continuously. How current the information is determines how quickly risks become visible.
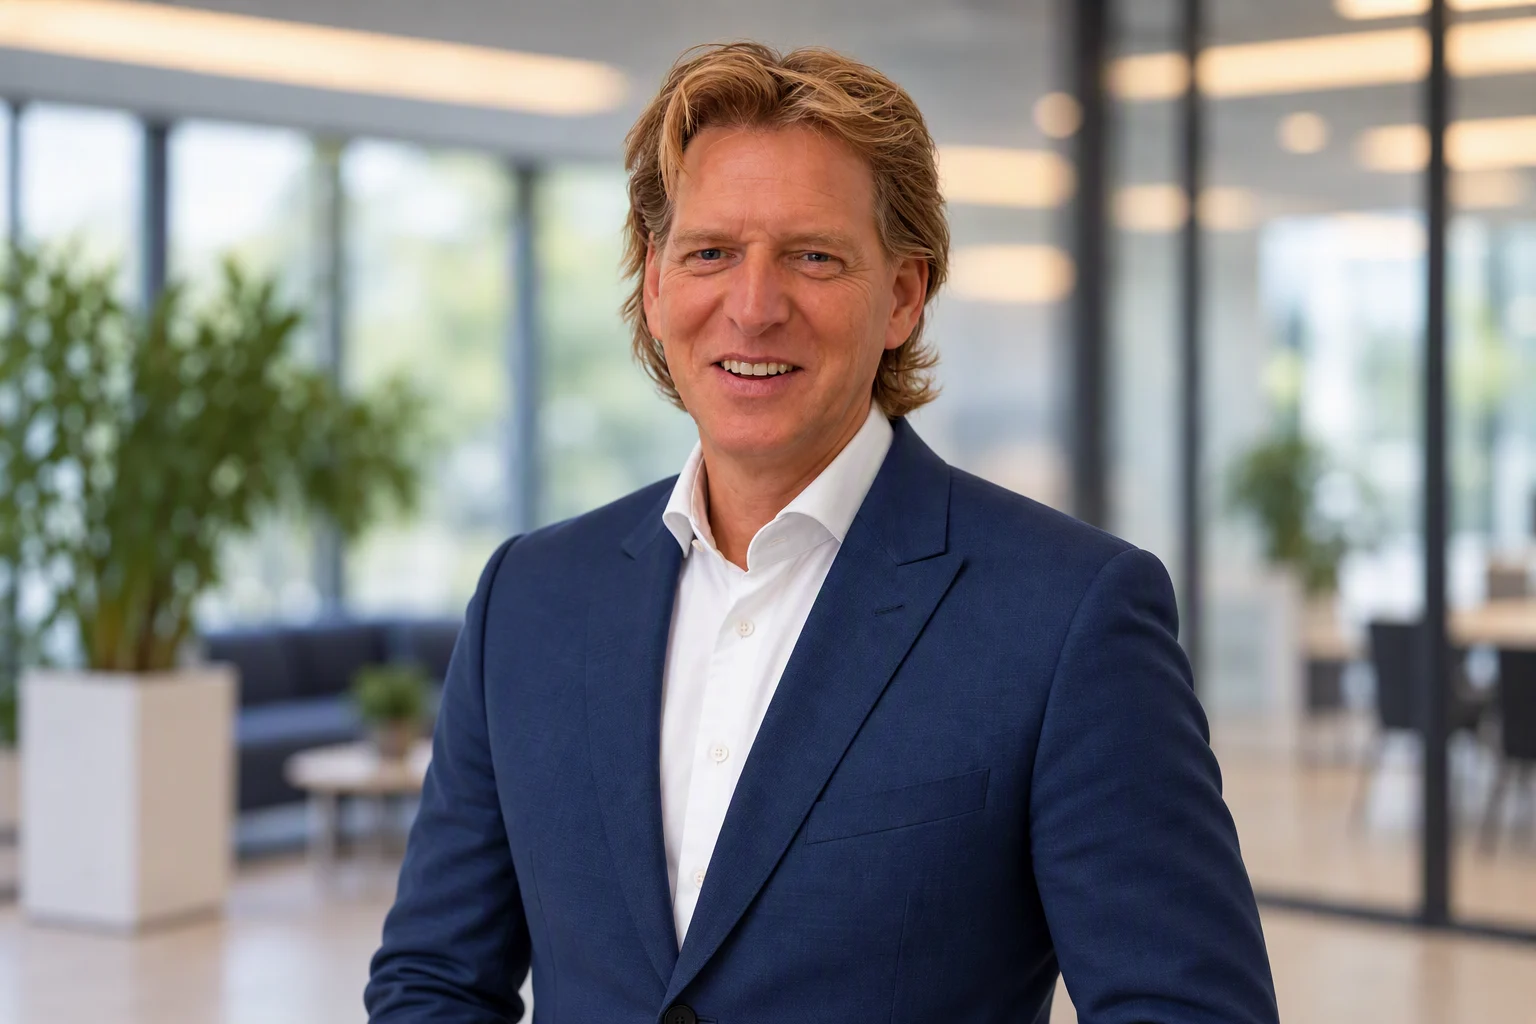
Marco Verbeek has worked at ABN AMRO since 1994 and helped establish the Client Audit Team around fifteen years ago. He was also involved with Finterface from an early stage, from the first presentation to a pilot involving five clients and the platform’s subsequent development. His story shows how inventory monitoring is evolving from periodic checks to daily insight and an increasingly targeted focus on risk.
“Here’s Excel. Good luck with it”
When Marco and a colleague set up the audit department, there was no blueprint to follow. Processes, analyses and reports all had to be built from scratch.
“We started with nothing. We had no analysis tools, no audit-specific reporting and no processes for how to conduct a conversation like that with a client. In a large organisation, a team of two or three people isn’t going to get any IT support either. It was basically: here’s Excel, good luck with it. It really was pioneering work.”
The approach was refined further over the years, but one fundamental characteristic remained: most of the information used to manage risk was periodic.
“We received an Excel file from the client and did our best to analyse it as thoroughly as possible. But it was still only a snapshot.”
Daily insight changes the risk picture
Marco was introduced to Finterface through his director at the time. Founder Frank Husken presented the idea for a platform that could make inventory information available automatically and on a daily basis.
“They didn’t really have anything yet. Just a presentation showing what they wanted to build. But I was completely sold on the idea.”
For Marco, the main appeal was the difference compared with the existing form of monitoring.
“Our monitoring department analysed an Excel list every month and then performed an availability calculation: how much financing does that inventory support at that particular moment? Finterface would do that every day, in a standardised way. What’s not to like?”
He illustrates the implications for risk management with a simple example.
“Suppose you receive a balance of ten million on 1 July. At the end of July, the client goes bankrupt. You haven’t received a new balance yet, and the inventory has fallen to just five million. You think you have ten million, when in reality only five million remains. Daily insight largely mitigates that risk.”
With daily information, the delay between what happens at the client and what the bank can see becomes much shorter. Having up-to-date information therefore becomes an integral part of risk management.
Introducing the platform within the bank nevertheless required considerable persuasion.
“A bank is very accustomed to building things itself, including its own software. My manager strongly championed it, but you still have to convince a lot of people at management level.”
A pilot involving five clients subsequently demonstrated how the Finterface concept worked within ABN AMRO’s day-to-day practice. This marked the beginning of a close collaboration, with the bank regularly providing feedback and requests based on its experience in inventory finance.
“They always listened very carefully to what we needed.”
From digitise to analyse
The practical experience gained during the pilot continued to be used to refine the platform. ABN AMRO contributed requirements relating to onboarding, dashboards and controls. A risk score developed by the bank was also incorporated into the platform.
As more data became available on a daily basis, the focus began to shift. For Marco, the next phase is no longer simply about digitising information, but primarily about what can be done with it: further validating data quality, identifying anomalies and determining where additional attention is needed.
“I call it ‘from digitise to analyse’. Initially, the goal was to connect clients. The main thing was that we received the data electronically.”
The next step is therefore not simply about having more data. It is about its quality and determining which anomalies require attention. The risk score should help translate those signals into action more explicitly.
“We wanted a risk-based approach. The computer says: do something. So, if we exceed a certain score, we as a team need to take action. That might be a full-scope audit, but it could also mean selecting one specific area because we can see that’s where the risk lies.”
This also changes the fundamental approach to auditing. Instead of reviewing every client according to a fixed schedule, capacity can be deployed in a much more targeted way.
“There’s no point in visiting a client every year only to hear the same thing each time: everything is fine, nothing is wrong. There are clients where things aren’t going well. That’s where I want to be.”
“There are clients where things aren’t going well. That’s where I want to be.”
Understanding what is actually there
One concrete example is the age of inventory. In inventory finance, this is an important indicator of the quality and potential saleability of the collateral.
The longer inventory remains unsold, the more relevant it becomes to ask whether it is still marketable and what value the collateral actually represents. Marco gives a practical example:
“Suppose a company buys a desk and it’s still sitting there a year later. You start to wonder: why is that desk still there? And if I had to sell it now, what would it still be worth?”
Previously, the bank depended on the information a client could extract from its own systems. That information was not always available. According to Marco, Finterface can derive inventory age from the available inventory data in almost every case.
“Finterface has been able to generate that insight in, I think, 99 per cent of cases, even when some clients couldn’t generate it themselves. This gives us an increasing level of insight into the quality of the inventory we finance.”
It illustrates what digitise to analyse is about: not collecting as much data as possible, but using current and reliable data to determine where an anomaly exists and what it means.
A shared view for all parties involved
The same information base can also be used by other parties involved in a financing arrangement. One example is a club deal, where several banks are involved and ABN AMRO may act as the agent responsible for monitoring.
“Other lenders can then be given access to the portal. Previously, this kind of information was held in Excel and could sometimes be difficult to explain. In Finterface, you have a clear overview and can click through to the details you want to see. Everyone is looking at the same information.”
External valuers can now also be given access to the portal. Instead of receiving a standalone inventory list for one specific point in time, they can analyse the available information over a longer period and assess it using their own expertise. Their evaluation therefore adds an additional layer to the daily monitoring.
A shared view does not remove the distinct roles of the parties involved. Instead, it allows each party to perform its own analysis and assessment using the same underlying information.
Automating what can be automated, interpreting what matters
As systems collect, structure and analyse more information, Marco believes human expertise can be applied where it adds the most value: understanding what the information actually means.
“If I can receive a standard analysis straight away, all I have to do is interpret it. And that’s where our strength lies. In the interpretation, really.”
Marco also sees potential for AI, for example in automatically turning conversations with clients into an initial report. In his view, the final assessment remains a human task.
“Drawing conclusions is still difficult for AI. Visiting a client and having the conversation is our speciality. We know which questions to ask and when we need to probe further.”
“Our strength lies in the interpretation.”
For a department facing capacity constraints, automation is therefore not only about efficiency. Spending less time collecting information and performing standard analyses creates more room for conversations and professional judgement.
“This process of automation will help us do what we’re good at: visiting clients, properly interpreting the data and the conversations, putting our findings on paper and then sharing them with the organisation.”
From pilot to firm requirement
What began as a way to make inventory information available on a daily basis is evolving into an approach in which reliability, analysis and a targeted focus on risk increasingly come together.
When asked what he would miss if Finterface no longer existed tomorrow, Marco surprisingly does not begin with data or risk scores.
“The people. The relationships have always been very good and warm, and that’s what I would miss first.”
He then turns to the practical business consequence.
“From a work perspective, you would simply no longer have a proper view of those financing arrangements. And, to be honest, I would question whether we should still provide them at all if we didn’t have that insight.”
That brings the story full circle. Finterface began as an idea that Marco and his colleagues were allowed to test in a pilot involving five clients. Today, his starting point has been reversed. For future inventory financing arrangements, daily insight is no longer an optional extra:
“For me, it is an absolute requirement that this is in place.”
See how Finterface can turn periodic asset monitoring into daily insight, helping you identify risk sooner and focus attention where it matters.